Sensex Gain 31 points, Nifty at 25,299; Tomorrow Nifty Prediction
Market Outlook for November 13: Benchmark Indices End Marginally Higher Amid Volatile Trade; Key Levels to Watch on Sensex and Nifty
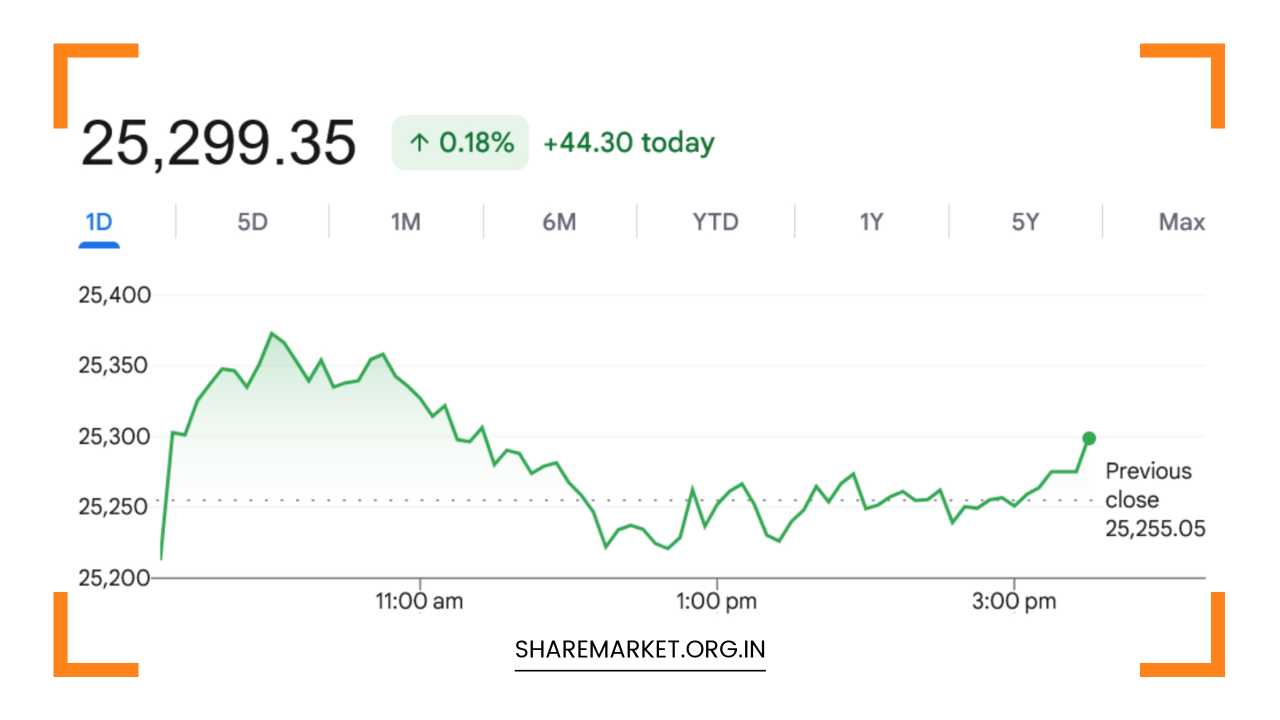
Indian benchmark equity indices managed to eke out marginal gains at the close of a volatile trading session on November 12, demonstrating underlying resilience even as profit booking at higher levels capped the day’s upside. By the closing bell, the NSE Nifty 50 settled just shy of the psychological 25,300 mark, advancing 44.30 points, or 0.18 percent, to end at 25,299.35. Similarly, the BSE Sensex navigated choppy intraday swings to finish 31.61 points, or 0.04 percent, higher at 81,911.01.
While the headline indices appeared largely flat at the close, action beneath the surface told a much more constructive story. Market breadth remained firmly in favor of the bulls, signaling healthy participation across the broader market. On the BSE, approximately 2,377 stocks advanced against 1,878 declines, while 195 counters remained unchanged. This outperformance in the wider market was clearly reflected in the broader indices, with the Nifty Midcap index climbing 0.85 percent and the Nifty Smallcap index surging 1.10 percent.
Top Movers and Sectoral Performance
Trading on November 12 was characterized by pronounced sector rotation, with financial and rate-sensitive stocks attracting strong buying interest, while defensive and commodity-linked counters faced selling pressure.
Among the Nifty 50 constituents, financial services and insurance heavyweights dominated the gainers’ list. HDFC Life Insurance, Bajaj Finance, Shriram Finance, SBI Life Insurance, and State Bank of India (SBI) emerged as the top performers, lifting the benchmarks out of negative territory during the afternoon session. Conversely, ONGC, Hindustan Unilever (HUL), Mahindra & Mahindra (M&M), Nestle India, and Power Grid Corporation bore the brunt of profit booking, ending the day as the major laggards on the index.
| Index / Sector | Closing / Change | Key Market Trend |
| BSE Sensex | 81,911.01 (+0.04%) | Flat close after erasing early intraday gains |
| NSE Nifty 50 | 25,299.35 (+0.18%) | Held near 25,300; broader breadth remained positive |
| Nifty Midcap / Smallcap | +0.85% / +1.10% | Outperformed headline benchmarks on strong retail/domestic flows |
| Nifty Realty | +3.70% (up to +4.50% intraday) | Top sectoral gainer on renewed buying momentum |
| Nifty Media & PSU Bank | +2.40% / +1.40% | Strong follow-through buying across state-run lenders |
| Nifty Bank / Private Bank | +1.00% / +0.87% | Provided crucial index support against defensive drag |
| Nifty Auto & FMCG | -1.00% / -0.88% | Dragged down by profit booking and margin concerns |
| Nifty Oil & Gas / Energy | -0.76% / -0.60% | Pressured by elevated global crude oil prices |
| Nifty Pharma & IT | -0.57% / -0.40% | Subdued action amid currency volatility and defensive rotation |
Sectorally, the Nifty Realty index stole the spotlight, rallying 3.70 percent (and touching gains of up to 4.50 percent during intraday trade) on the back of robust demand expectations and institutional accumulation. The Nifty Media index followed with a strong gain of 2.40 percent, while banking stocks provided steady structural support—the Nifty PSU Bank index rose 1.40 percent, the Nifty Bank gained 1.00 percent, and the Nifty Private Bank index added 0.87 percent.
On the flip side, the Nifty Auto index suffered the steepest decline among sectoral gauges, slipping 1.00 percent as traders locked in recent gains. Defensive pockets also saw outflows, with the Nifty FMCG index dropping 0.88 percent and the Nifty Pharma index shedding 0.57 percent. Meanwhile, rising input cost concerns weighed on energy counters, pulling the Nifty Oil & Gas index down 0.76 percent, while the Nifty Energy and Nifty Infrastructure indices fell 0.60 percent each. The Nifty IT index ended modestly lower, declining 0.40 percent.
Macro Drivers and Institutional Flows: What Lies Ahead?
Market participants are currently weighing strong domestic and foreign institutional inflows against nagging macroeconomic headwinds, resulting in a cautious, range-bound trading environment.
Commenting on the market’s trajectory, Vikram Kasat, Chief Business Officer, Advisory and Dealing at PL Capital, noted that Indian equities exhibited a cautious undertone throughout the session, surrendering a substantial portion of their early morning gains as traders booked profits at higher levels. However, he emphasized that the underlying health of the broader market remains intact, underscored by the outperformance of mid-cap and small-cap stocks alongside strong traction in realty and banking counters.
From an institutional standpoint, sentiment received a major boost from foreign portfolio activity. Foreign Institutional Investors (FIIs) infused a substantial ₹12,563 crore into Indian equities on November 11, signaling renewed appetite for domestic risk assets. Yet, global macro variables continue to keep upside enthusiasm in check:
-
Currency Pressure: The Indian rupee depreciated to ₹93.81 against the US dollar, raising concerns over imported inflation and foreign exchange outflows if the slide persists.
-
Crude Oil Prices: Brent crude oil hovered near the $92 per barrel mark, a level that poses fiscal and margin headwinds for oil-importing economies like India and directly weighed on domestic oil, gas, and energy stocks.
-
Precious Metals: In the domestic bullion market, both gold and silver prices remained under selling pressure, reflecting shifting global yield expectations and dollar strength.
Looking ahead to November 13 and the remainder of the week, Kasat highlighted that market direction will be dictated by four primary catalysts: the sustainability of foreign institutional investor sentiment, currency stability around current rupee lows, fluctuations in international crude oil prices, and the ongoing second-quarter corporate earnings season. While headline indices may consolidate in the near term, this stability creates attractive bottom-up investment opportunities in fundamentally strong, stock-specific plays.
Technical Outlook: Support and Resistance Levels for November 13
From a technical perspective, the market is locked in a classic tug-of-war between bulls and bears, awaiting a decisive breakout trigger.
According to Shrikant Chauhan, Head of Equity Research at Kotak Neo, benchmark indices spent the session oscillating within a tight, narrow band before the Nifty settled 44 points higher and the Sensex added 32 points. Analyzing the price action, Chauhan pointed out that the Nifty has formed a small-bodied candle on the daily chart, while intraday charts reflect clear indecision between buyers and sellers.
For day traders and short-term market participants heading into the November 13 session, technical levels will be critical in navigating intraday volatility:
-
Immediate Support Zone (25,150): On the downside, the 25,150 level on the Nifty has established itself as a crucial immediate support zone. As long as the index holds above this threshold, dips are likely to attract buying interest. However, a decisive breakdown below 25,150 could trigger accelerated long unwinding, dragging the index lower toward the 25,050–25,000 psychological support band.
-
Immediate Resistance Zone (25,400): On the upside, the 25,400 mark stands as the immediate hurdle for bulls. Supply pressure has repeatedly emerged near this zone. If the Nifty manages to stage a sustained breakout above 25,400 backed by strong volume and banking participation, the rally could quickly extend toward the 25,500–25,550 territory.
As long as the Nifty remains trapped within the 25,150 to 25,400 consolidation corridor, traders should brace for choppy, two-way volatility without a clear directional trend. Consequently, market experts advise adopting a selective, stock-specific approach—focusing on sectors showing relative strength like banking and real estate—while maintaining strict stop-losses until a confirmed range breakout occurs.